


Crypto didn’t lose its edge but it lost its monopoly. The same moonshot return profiles that once lived near exclusively in crypto now exist everywhere — in semiconductors, AI infrastructure, memory, space, and whatever narrative is next up on the Trump administration's agenda. The sharp capital that was always rotating among different cryptocurrencies saw the shift in the extraction pipeline and learned how to rotate elsewhere as DATs and boomers hoovered up supply locking in 1000+ baggers for OGs. And when these boomers arrived, they brought their DCFs.
The overwhelming trend of the last few years in crypto has been monotonically increasing financialization and integration with TradFi. But when the dreamers who got into Bitcoin and crypto at least a couple of cycles ago, these levels of adoption felt like pipe dreams. They spoke of pensions, corporates, and Nation State accumulation: OGs dreamed of dumping on them. Blackrock brought about the most successful ETF launch in history with over $63B in inflows in 2 years.
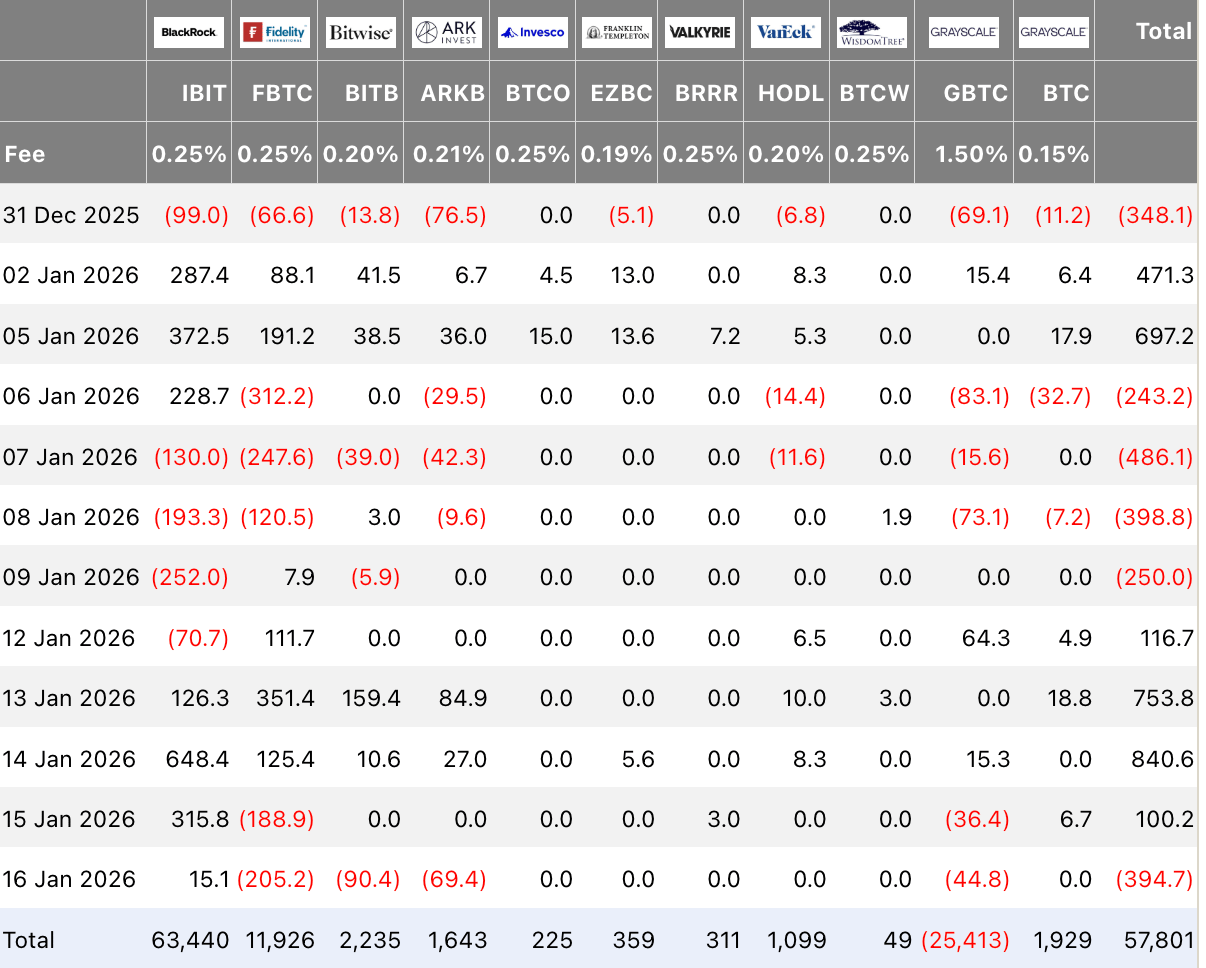
BTC ETF inflows for Farside
When Ethereum and smart contracts came around in 2015, it shifted away from who would buy and became increasingly about creating a whole new financial system on crypto rails. While there have been tons of ideas in crypto funded over these years, and most have flamed out in one way or another, the one that always made the most sense was backend financial infrastructure, or decentralized finance (DeFi). Long story short, it’s 10 years later and every big institution is involved and continuing to deepen and expand their offerings. Just yesterday, NYSE/ICE announced they were building a platform for 24/7 trading of tokenized securities with instant settlement and stablecoin funding.
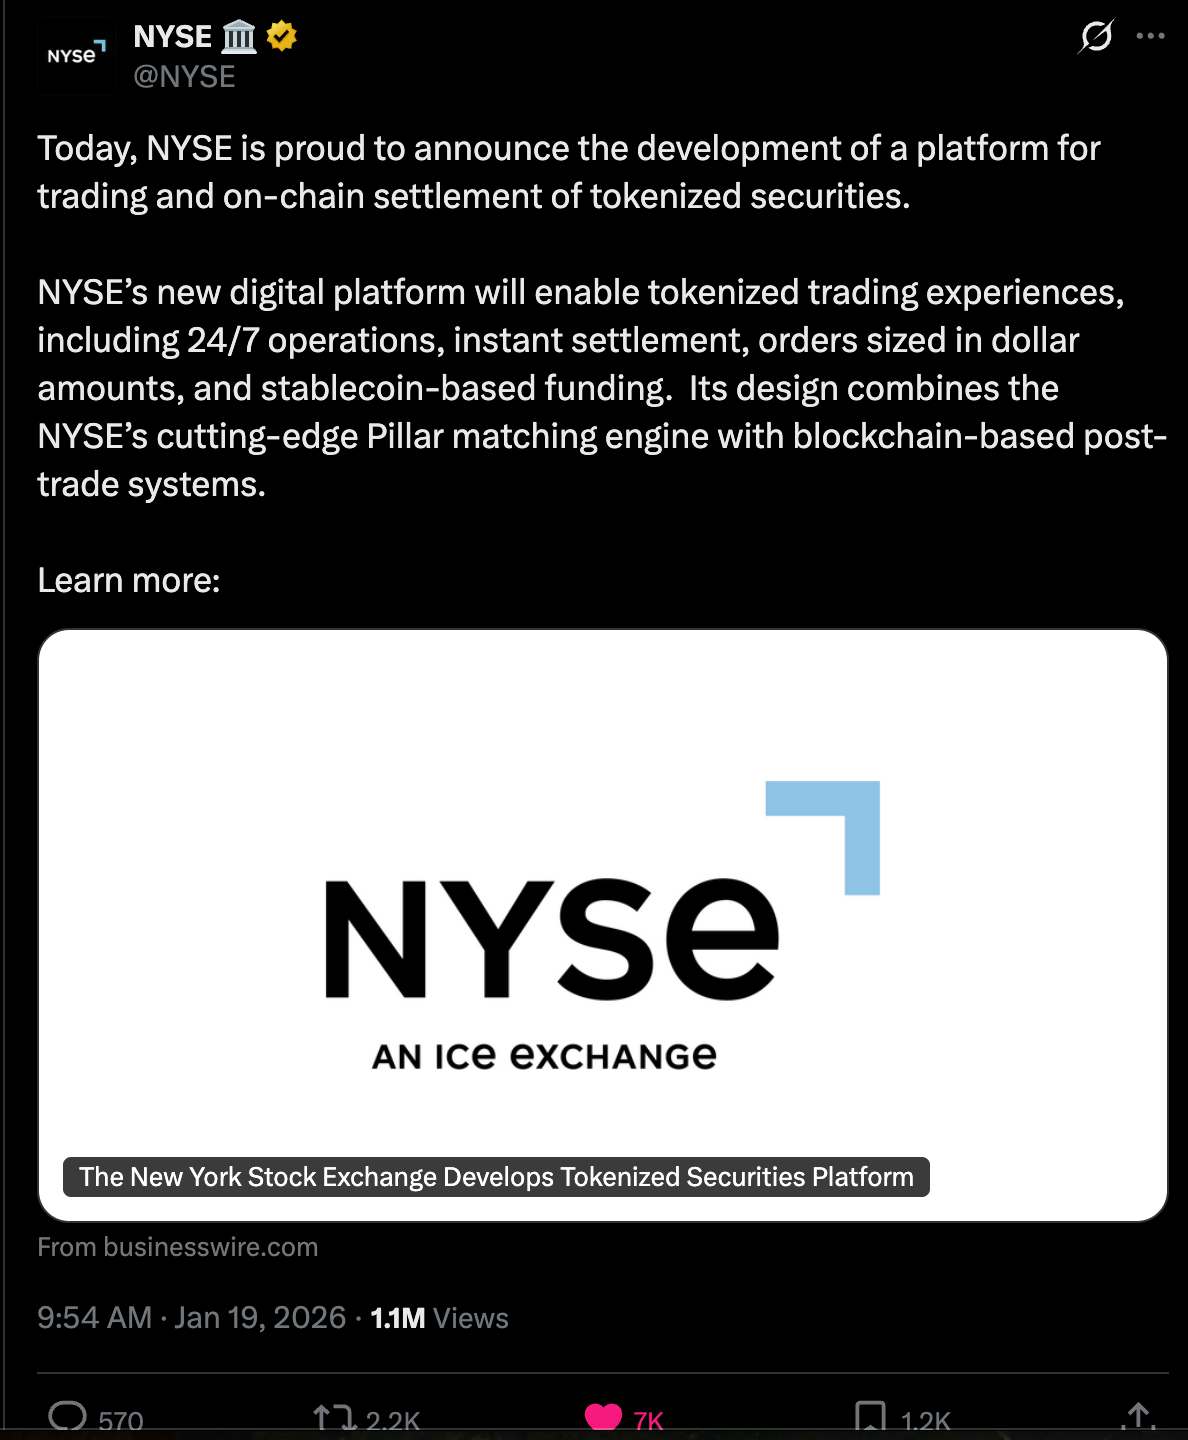
NYSE, an ICE exchange, plans to launch 24/7 trading on crypto infrastructure
In those 2012-2016 days, there were relatively few coins and starting valuations were low. As such, tremendous upside was available if you picked the right coin because it was truly early. The asymmetric upside was the biggest draw. As more people heard about success stories, they rushed in to try to capture some themselves in a modern-day gold rush.
Crypto Grows Up
The shift has been palpable in many ways including price action and sentiment. Mostly, the way altcoins have traded has been greatly underwhelming this cycle compared to those prior.
There are many reasons for this such as lowered barriers to launching tokens (launchpads) and improved extraction games (low float high FDV games and the zeitgeist moving people away from bidding them) that I’ve touched on in my prior articles “There is no PvE I Love you” and “The Sunk Cost Cage”. Links below if you’d like to revisit.
The Sunk Cost Cage:

There is no PvE I Love you:
As such, we’ve seen relatively few success stories outside of the majors. The most notable is Hyperliquid which provided huge returns for its early community. It’s also the poster-child for the “Return to Fundamentals” I’m going to discuss. Despite the incredible success of going from $0 to $24B FDV/$8B circulating cap, today Hyperliquid is nearly 60% off its all time highs. The key elements that allowed this success:
There is real demand for the product (perps) without incentives. Users find good liquidity for speculation and hedging useful
The product is very good
In turn, the product is able to generate significant fees (users will pay for it)
It had uniquely good tokenomics (no investors, team locked)
Revenue from product directly benefits token holders via buybacks
For a long time, I expressed the idea that any crypto product traded at 10-10,000x any reasonable valuation of its web2 or TradFi counterpart simply for being crypto.
My argument is that the combination of boomer/TradFi adoption and the declining prospects of 99% of altcoins ushered in an era where altcoins will be forced to compete via traditional business metrics like cashflows rather than vibes or hopes and dreams. The premium just for using crypto has eroded tremendously, and this is a good thing.
The Stonk Market and Rolling “Bubbles”
While crypto was once the main arena for asymmetric upside, we’ve seen a shift to the stock market with many cryptonatives having fully shifted their efforts over to traditional markets. And it’s hard to blame them. Look at some of these successes that were available to all.
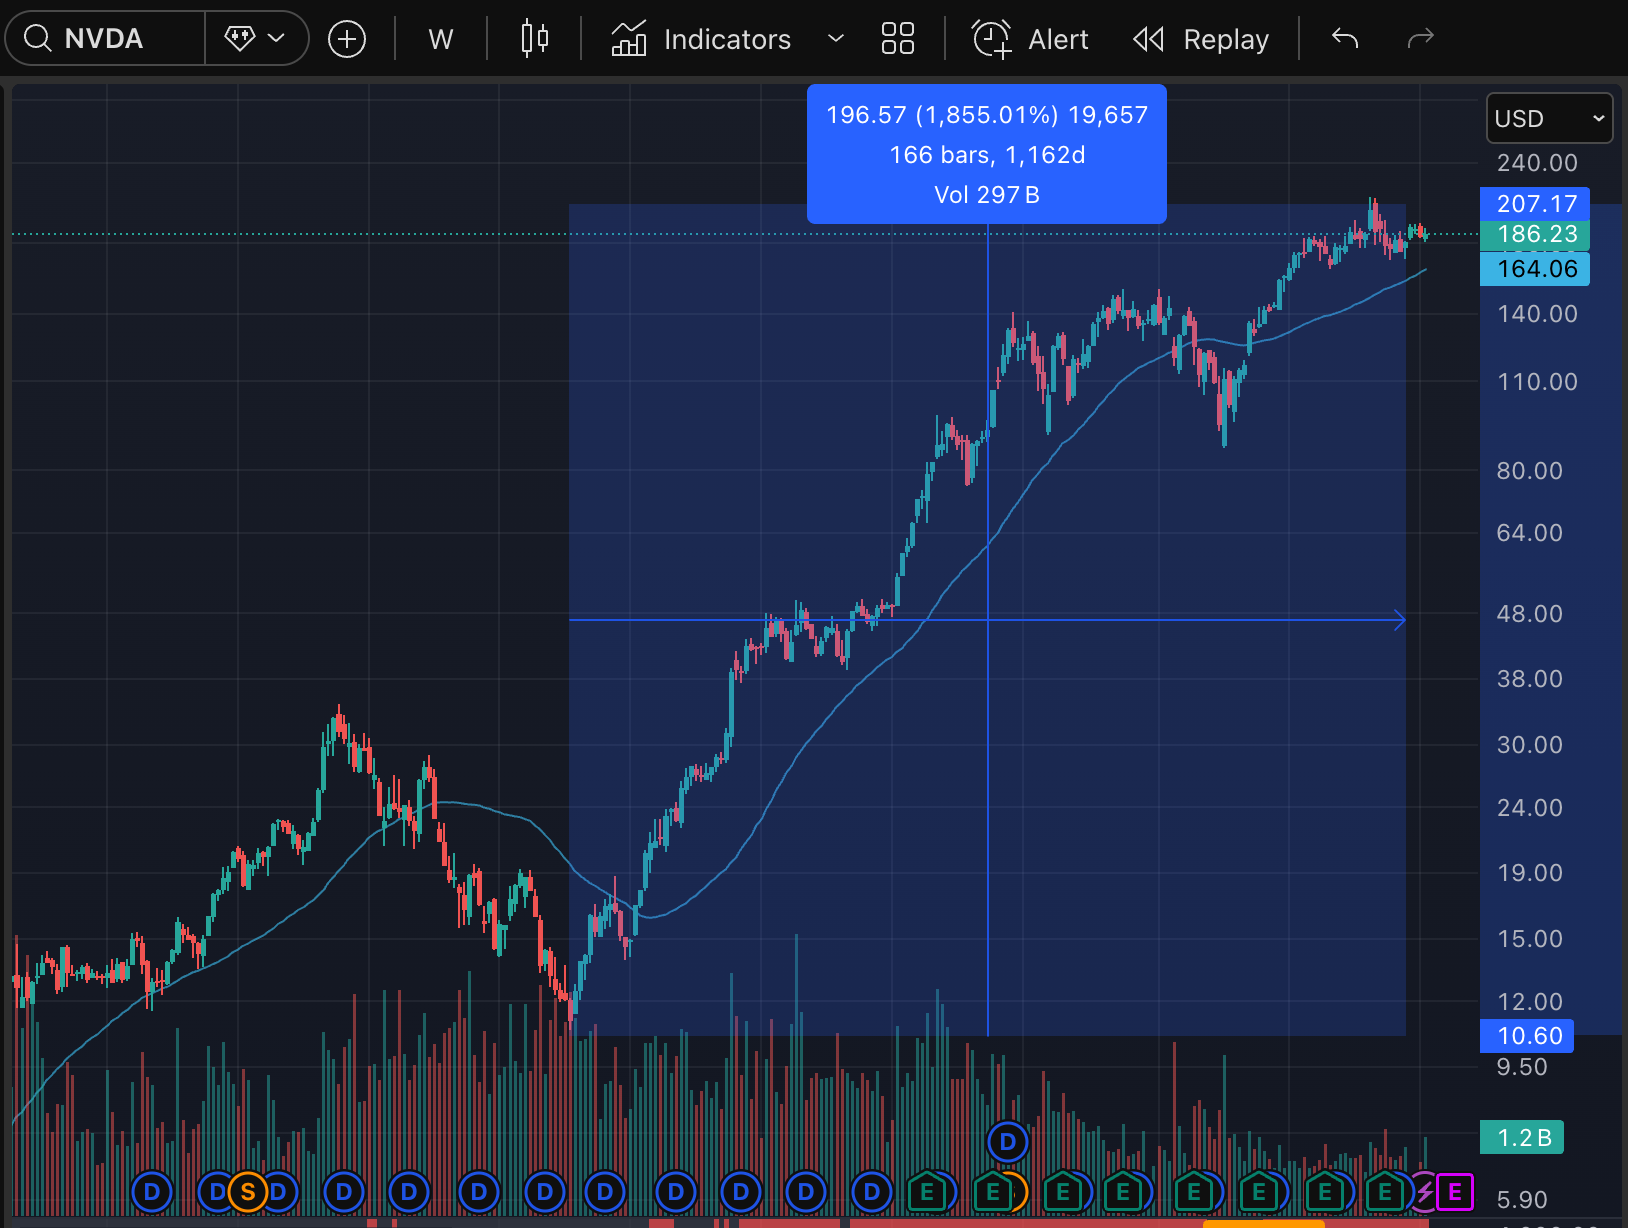
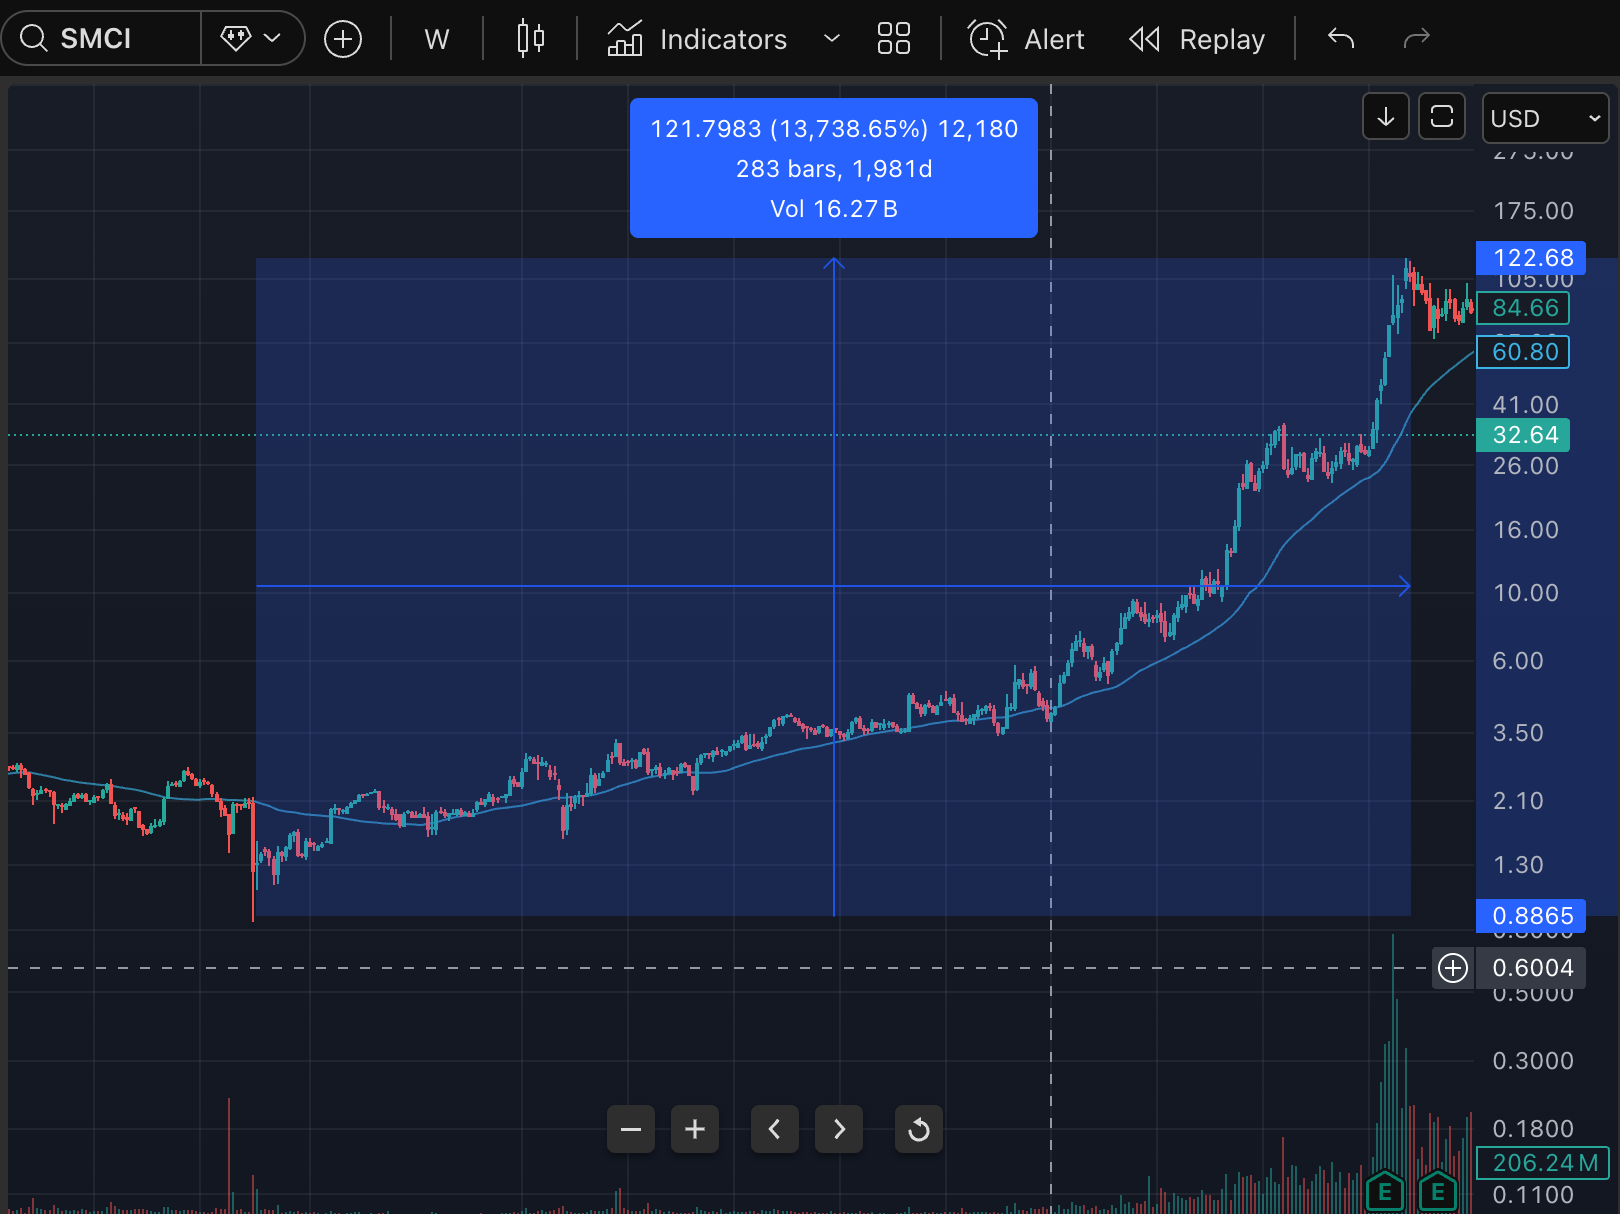
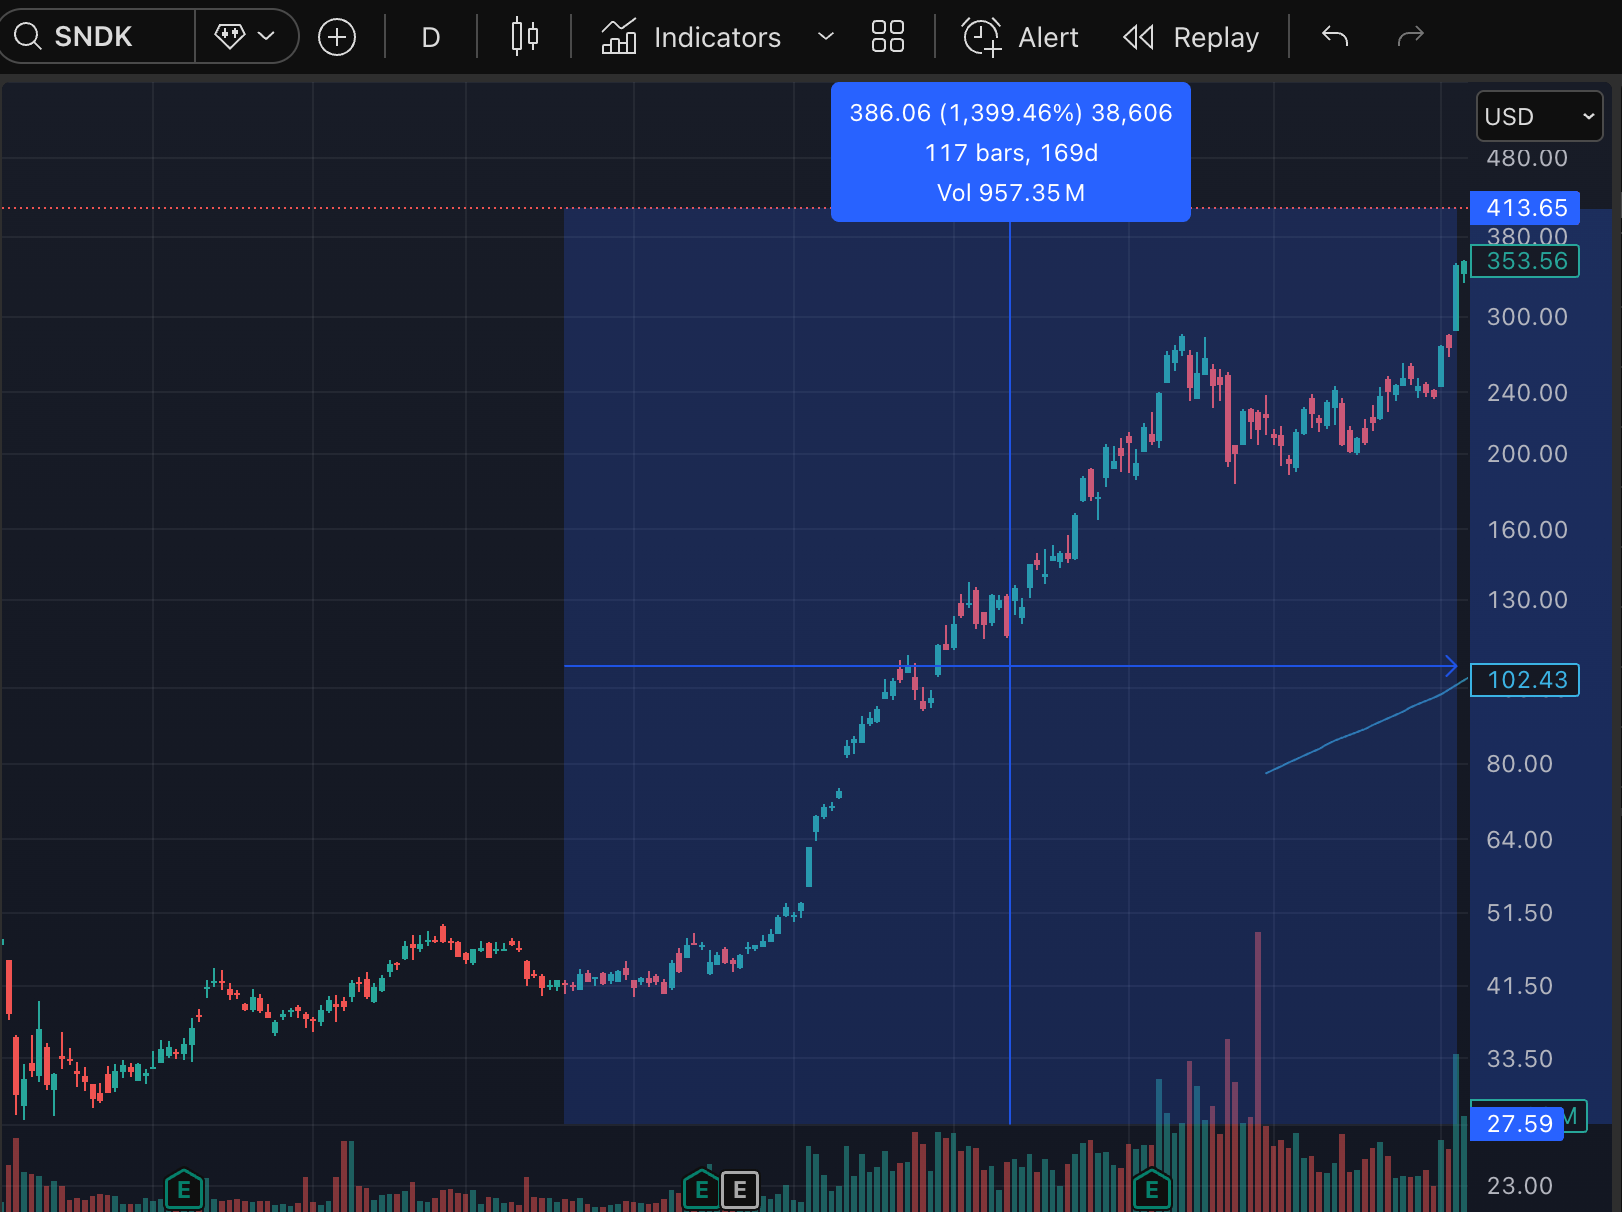
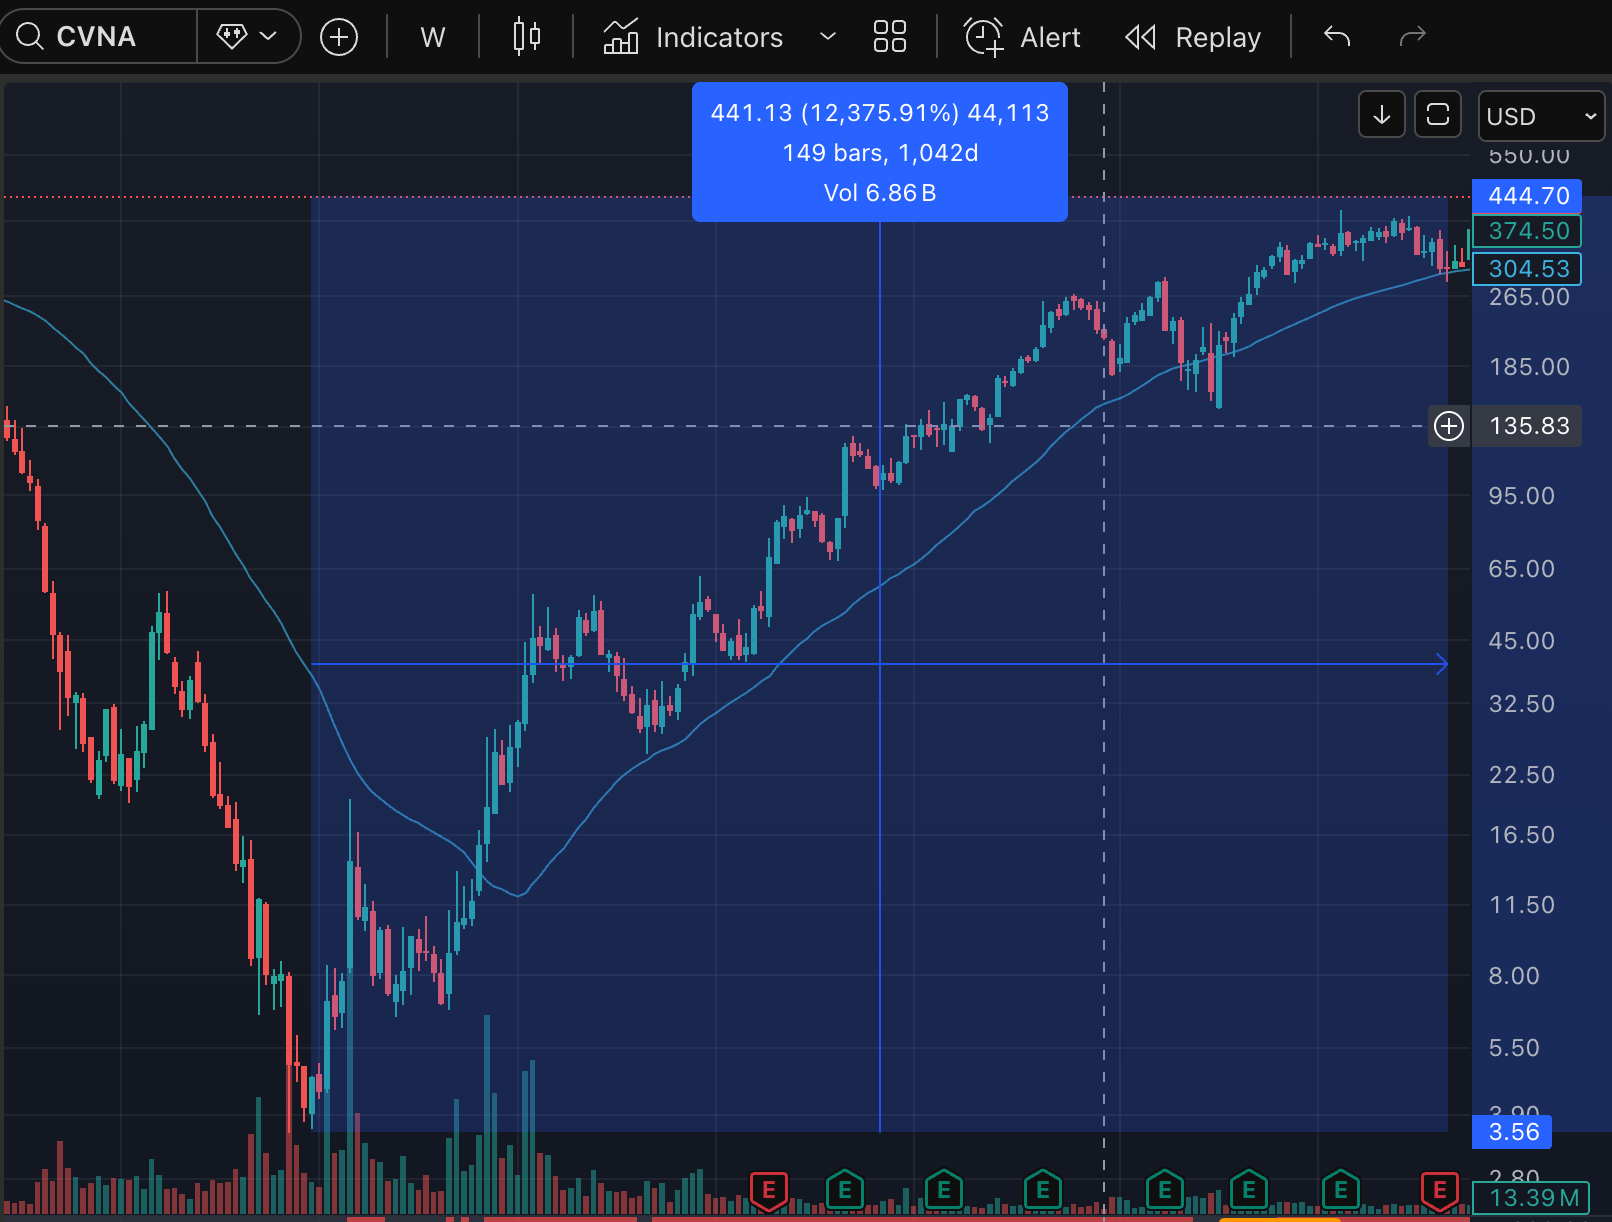
Asymmetric upside available to retail investors on stocks like NVDA, CVNA, SMCI and SNDK
With speculative dollars being channeled towards things that appear to have had much better risk:return profile than altcoins (many AI-adjacent stocks and precious metals), it’s no surprise that there aren’t as many dollars chasing altcoins anymore. Bubble chasers, or as GCR once coined, “Generation Moonshot” have increasingly found rolling bubbles they can participate in from the comfort of their own brokerage account.
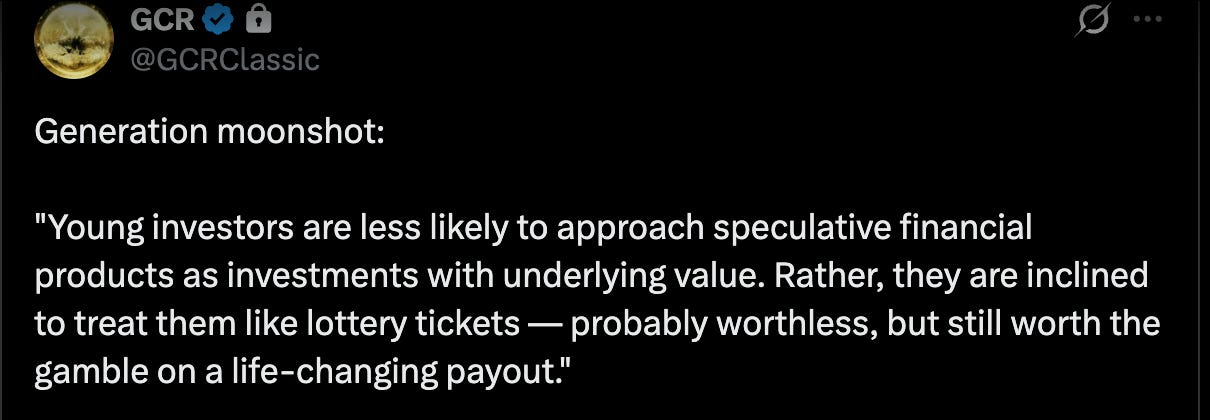
About a year after the Gamestop saga, it was clear the game had changed
While calling them “probably worthless” isn’t exactly accurate, the gist of it remains in that there are large swaths of people just trying to chase the fastest horse for quick capital accumulation and compounding rather than disciplined waging and studying Bogleheads.
And this idea of the stock market becoming increasiningly gamified and attention/narrative based is yet another reason that will force the altcoin complex to compete on real fundamentals like earnings. Crypto is no longer the hot sector (relative to things like AI, robotics, and space) that sucks in all the speculative, bubble-chasing capital. Most things will dwindle to zero and be abandoned as there is less propensity for capital to prop it up. Few will be able to survive and they’ll do it by making money sustainably.
The Shift
All of this calls for a clear need to approach crypto trading and investing differently than most [even successful] people did in 2009-2021. The broader thesis is the Boomerification of the crypto industry via deeper TradFi integration. In such a world where you can trade BTC, ETH, SOL, gold, NVDA, TSLA, GOOG, and any other equity on the NYSE all in one account, all that will really matter outside of non-sovereign SoV coins are things that can sustainably earn fees to justify their valuations.
The existence of such a thing validates the 2015-18 era idea that backend financial infrastructure was a good use case smart contracts. If you still want to put money behind that thesis, it makes sense to me to focus on the picks and shovels that enable it. Much like you could invest in IBKR, you can invest in crypto products and protocols that are able to earn fees based on trading-adjacent activities.
These are not small opportunities. Many crypto protocols are still quite small in relation, if you can envision a world where finance moves fully onto crypto rails.
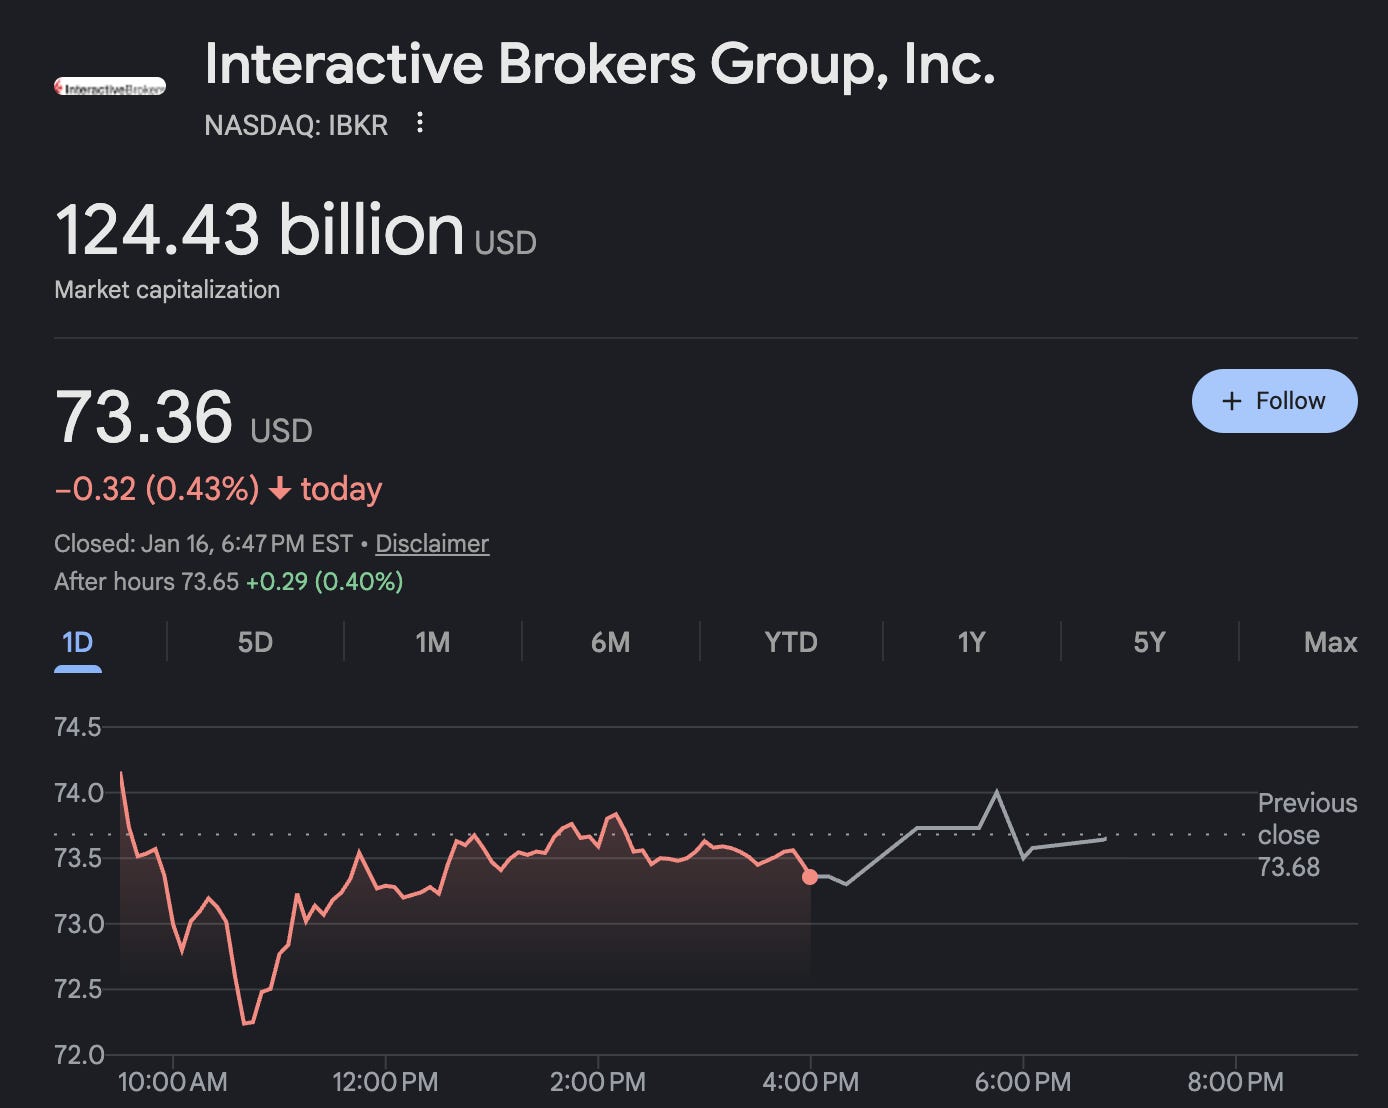
Interactive Brokers market cap
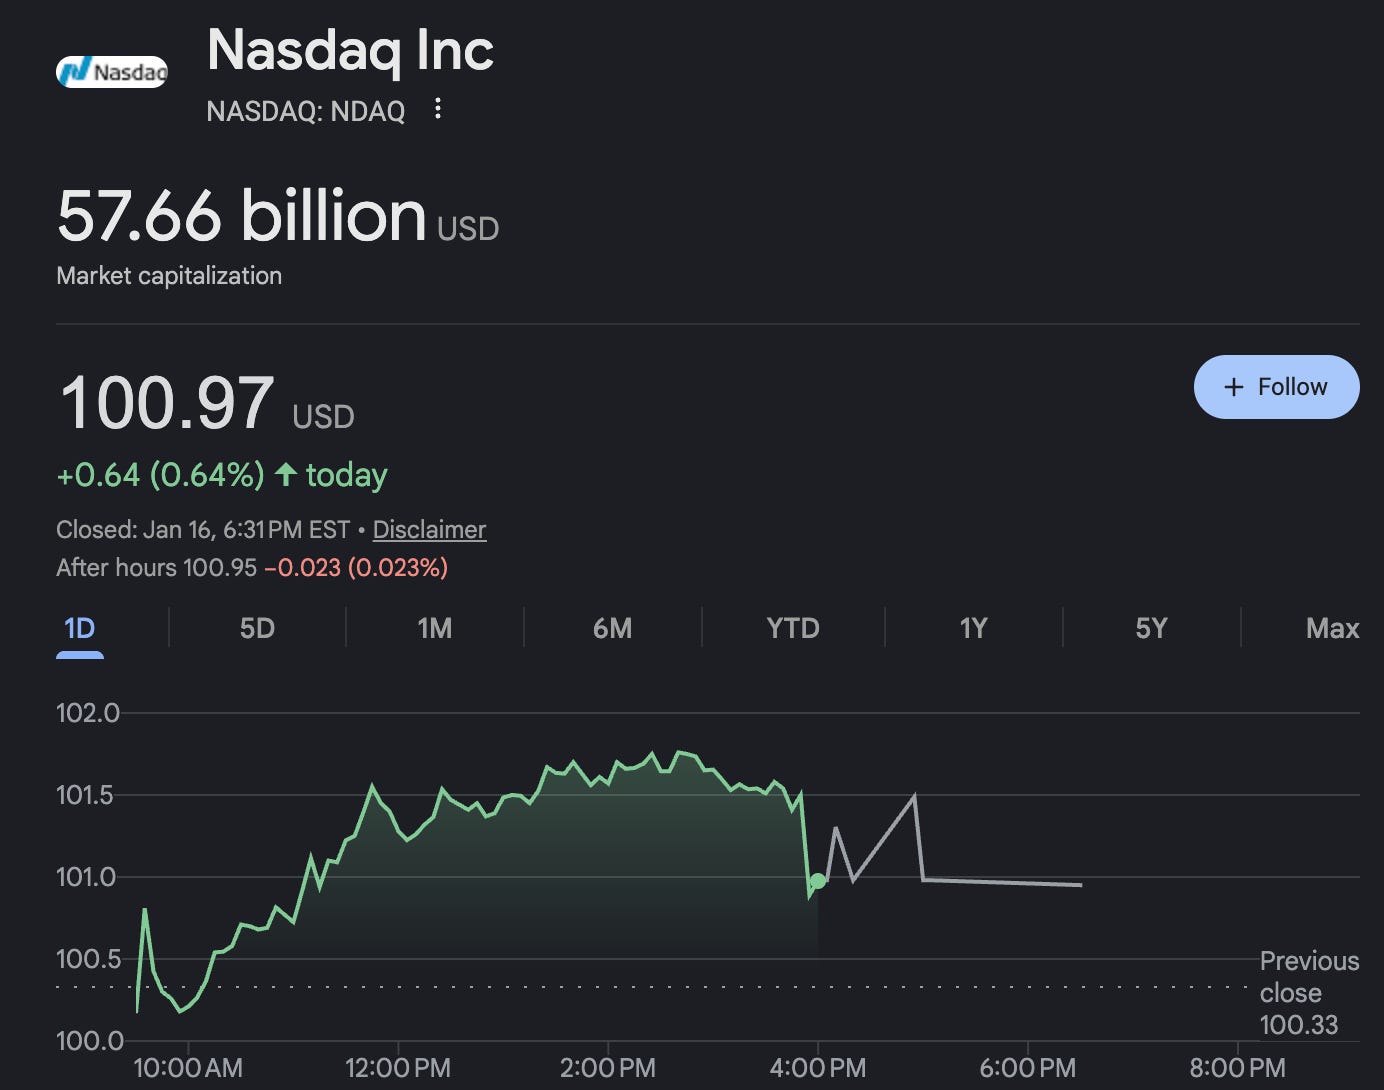
NASDAQ market cap
I’ve identified the 4 verticals that I believe are worth finding investments in. They are: (1) exchange, (2) lending, (3) RWA, stablecoins, and tokenized assets (especially equities) and (4) Interoperability
I’m not going to go into detail on (1) and (2) because I believe they’re pretty self-explanatory and the players and protocols (ie, Binance/Bybit/Coinbase/Hyperliquid/Lighter etc and Aave/Maker/Morpho) are well understood and in much more mature states. However, the opportunities in (3) and (4) I will expand upon.
RWA, Stablecoins, and Tokenized Assets
Stablecoins have gotten a lot of hype the last couple years. With a market structure bill expected to pass sometime this year, lots of different players are attempting to carve out their role and investments in the growing stablecoin trend. A lot of cryptonatives have lamented about the difficulty to get exposure to this trend as many of the best opportunities weren’t easily accessible (especially the two giants, Tether and Circle).
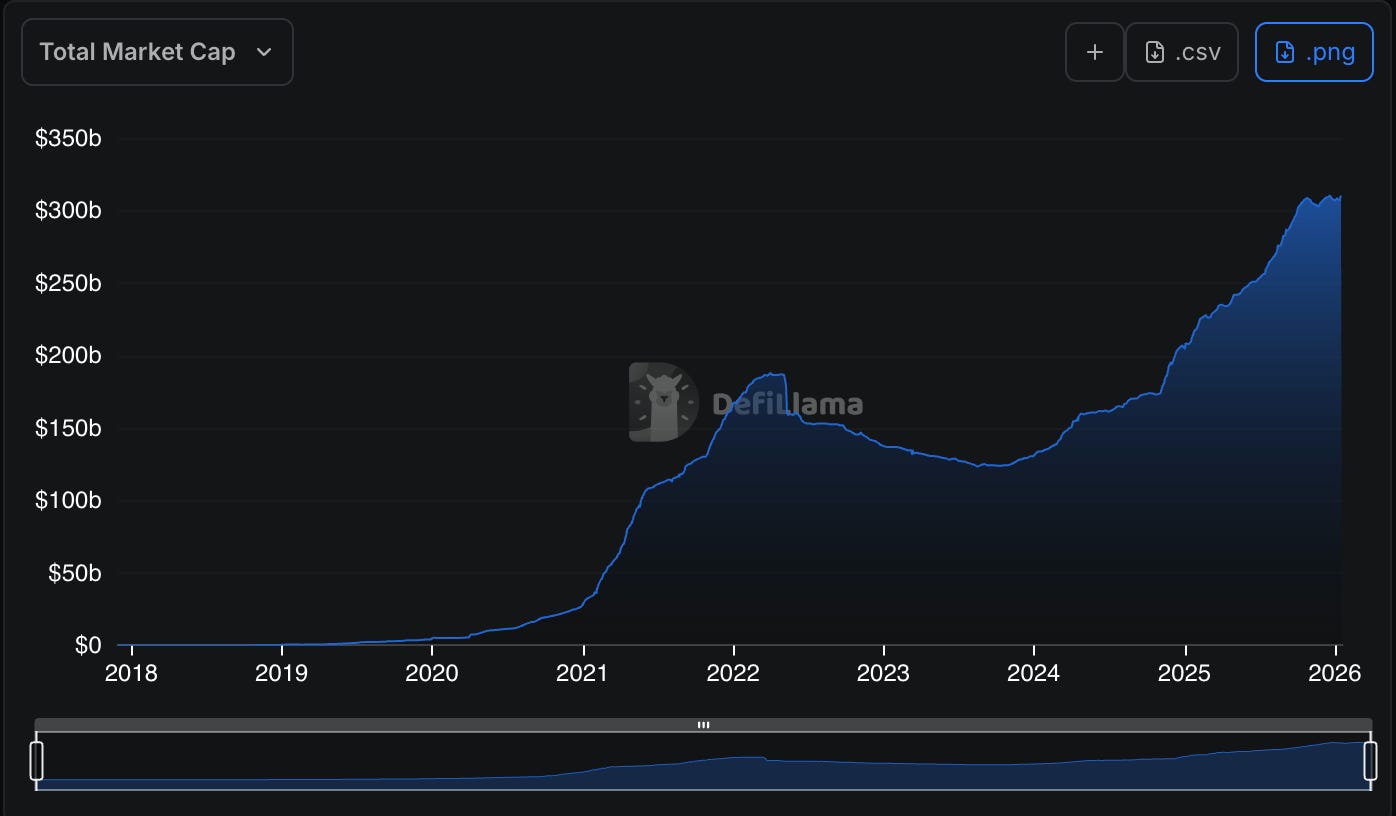
Stablecoin market cap has grown from essentially 0 to $311B since 2018
Another project that interests me strongly in this area is Superstate, founded by Compound founder Robert Leshner. Unfortunately I do not have investment exposure to this. I find it uniquely interesting because they’ve built the technology and compliance around issuing real tokenized shares on the Ethereum and Solana blockchains rather than some random wrapper. This will allow companies to issue real shares on crypto rails and even open up the possibility to do things like conduct IPOs or other fundraises. The combination of this, strong investors/partners, and real longtime cryptonative leadership should make them a key player in this vertical over the years. There are also early stage blockchain projects incubated by Tether: Plasma and Stable. As of yet, it is unclear exactly what their plans are with these, but it should be noted that these are the only two they funded.
InterOp and the LayerZero Opportunity
This is a pretty forgotten sector overall, but with every institution having their own offerings, from stablecoins to exchanges to ETFs and structured products, there will need to be a dominant standard for it all to work in a user-friendly way.
Much of the information that follows is available in this podcast with the founder:

While there are other interoperability protocols, LayerZero and its OFTs dominate marketshare across different metrics.
First is just the chart as a pure technical setup— it broke out of a consolidation range, retested and bounced, good setup for ~$2.30-2.50 at least. Showing great local strength as one of the only tokens that’s up this week and fully recovered the dip last night when BTC plunged from $95k to $92k taking altcoins down with it. Derivatives funding is also negative, likely due to the spot bid from buybacks/Labs/long-term investors.
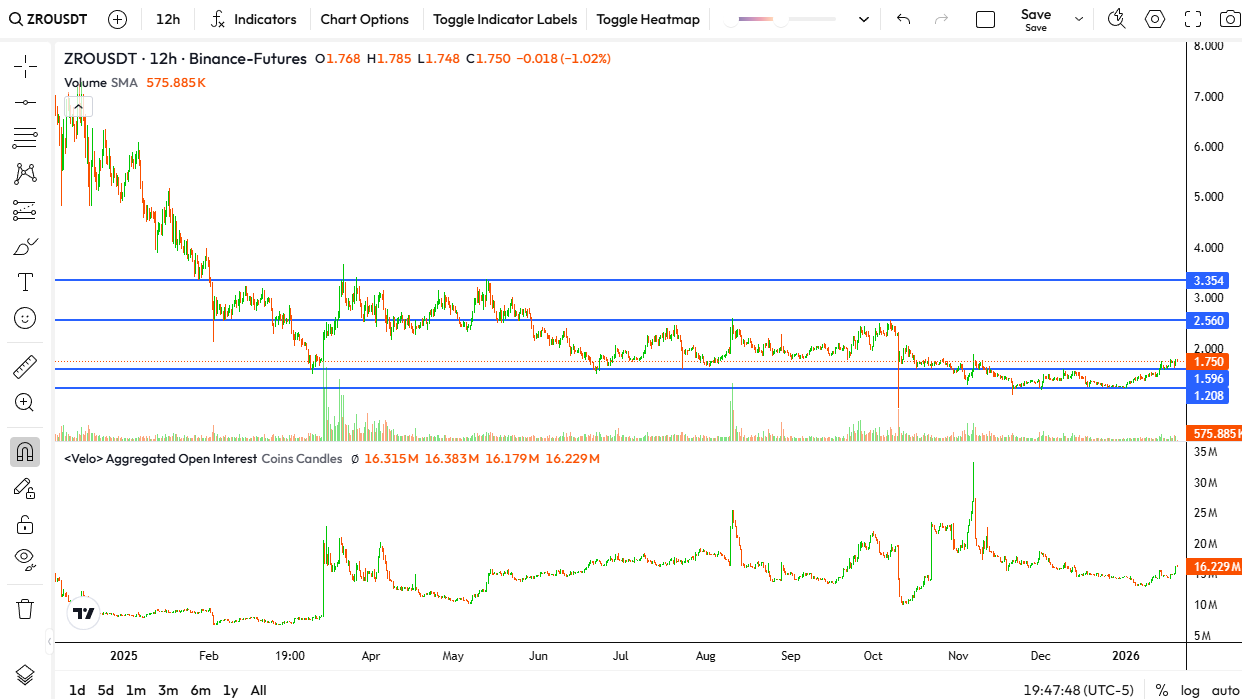
HTF Chart
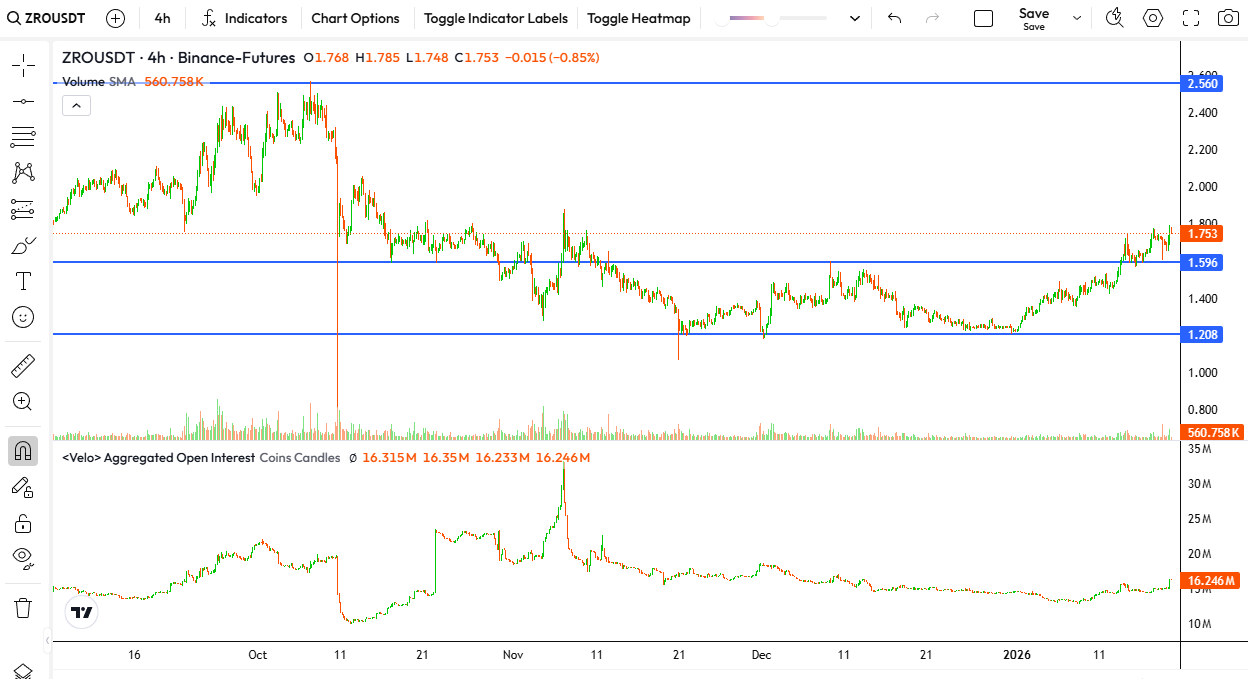
4h Chart
One of the most common problems across the altcoin complex is the scores of investors, team members, and foundations just constantly blading the price down as tokens unlock. However, the LayerZero situation is unique.
they cleaned up their token distribution by letting the investors who wanted out, out. a16z for example bought $55m more and relocked for 3 years in 2025.
LayerZero Labs (a standalone entity that sustains itself through functions that benefit the LayerZero network) bought back tokens to put on their own balance sheet ($10m in November and said they’d continue to add)
they didn’t create any DATs for the simple reason that they’re not willing to sell at this price, let alone a discount. Very little or no insider selling. Actual insider buying instead of constant sell pressure.
LayerZero recently unified their products via acquiring Stargate, their bridge offering. Stargate revenue is buying back
currently. Currently it’s 50% of revenue but in a couple months it will be 100%. Founder is predicting $100m run rate by end of year (see podcast linked above, around the 36 minute mark). Even half of that would be very substantial given current cap. Details of buybacks are explained and documented here:
all new product lines go towards buying back
. Founder suggested they have multiple things in the pipeline that could be 9 figure ARR opportunities. Also something very big coming, I don’t know what it is, but has been alluded to in podcasts as probably being TradFi adjacent and they scheduled an announcement for February 10th to share what they’ve been building for the last 2.5 years
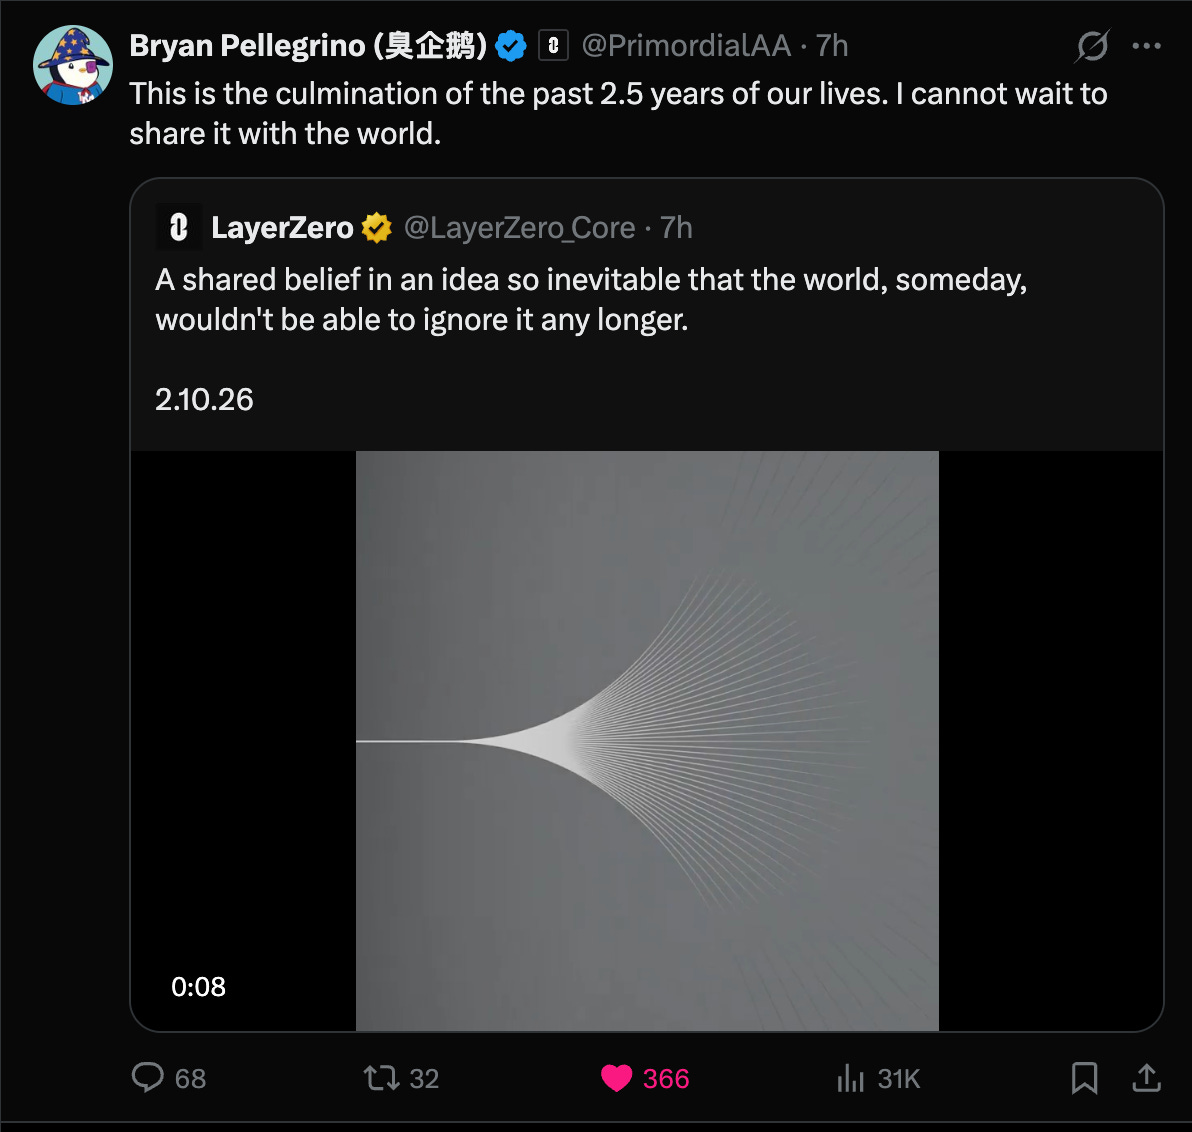
Announcing an announcement in true crypto fashion
fee switch vote for LayerZero comes up again in June. It may not succeed this time but it’s easy to imagine a future where a LayerZero message has a very small cost that adds up across tens of billions of transactions. This would add to the existing buyback sources.
my broader thesis is “the boomerification of crypto” where crypto -> Trad finance. LayerZero has the supermajority of market share in interop. I believe interop is a clear as day “pick and shovel” for the fully boomerified version of crypto I expect to continue to unfold. It also has stablecoin adjacency.
it will not take much for the buybacks flywheel to become extremely significant compared to current float and lack of insider selling. Unlocks have not impacted the price for several months now.
Wrapping Up
For better or for worse, crypto is a lot more boring than it used to be. Memecoins and alt L1s don’t have the same motion they did in 2021-2024. Even competent perp DEXes seem to be exhibiting the all too familiar euthanasia coaster pattern.
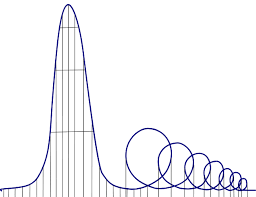
Each successive loop lower than the last
There may still be hope for something undiscovered (maybe something AI-native) but my base case is less romantic. The next generation of successful crypto products will not be interesting to trench rats who treat every new meta like the second coming of Christ. They’ll be boring things that are appealing to boomers because they make money. That’s what happens when boomers show up. They don’t buy vibes; they buy cash flows. In such a world, it only makes sense to barbell non-sovereign SoV contenders (BTC + maybe privacy coins) and industry picks and shovels that can benefit from earning fees through trading and trading-adjacent activity.
Generation moonshot is absent, not dead -- and it only reactivates if crypto earns it via something truly novel and useful.
_____________________________________________________________
Disclosures: Nothing contained within this article is investment advice or an endorsement of any product/project. At the time of writing, the author holds liquid positions in $BTC and $ZRO as well as various private investments. All positions are subject to change.